The cost of living crisis has been with us for a few years now, but many people still don’t fully grasp what’s actually going on and how to effectively deal with this problem.
If you want more about the causes of this cost of living crisis, check out my article The Cost of Living Crisis explained in one chart.
For now though, let’s focus on my top 5 solutions to help pull you out of crisis mode and get you back in control of your money, so you can stop worrying about the cost of living and enjoy life again.
Table of Contents
Cost of Living Solution #1 – Use the savings product that is the best long-term store of value (physical gold)
Most people save their money in their national currency – dollars, pesos, pounds, euros, you name it. This strategy is akin to shooting oneself in the foot. It hurts.
You see, national currencies come in a few flavours, but almost every flavour is made from the same unhealthy slop – that slop being debt. Debt that loses value day-by-day as more people use credit for unproductive purposes like their home, their car, their 65 inch OLED TV and (god forbid) their groceries.
Bank deposits are debt. Whether it’s a high-interest-bearing term deposit, mid-interest-bearing savings account, or a zero-interest transaction account – all are debt. A deposit is a loan to the bank, where you have a claim on the funds and a right to withdraw those funds as banknotes or coins.
The banknotes are also debt. A liability of whichever Reserve Bank, Treasury or banknote printing company printed / authorised them.
The coins are one of the few flavours of currency that aren’t debt, but the base-metals that make up most circulating coins aren’t rare enough or corrosion-resistant enough to be great stores of long-term wealth.
The only currency that has stood the test of time and kept its purchasing power intact for over 2,500 years is gold. Yes, it can have short-term swings and drops from time-to-time, that’s why it’s not a short-term asset to be speculated on. It’s a buy and hold savings vehicle. The only time to sell gold, is when a better opportunity like a cash-flowing asset comes along.
Look at a chart of gold prices.
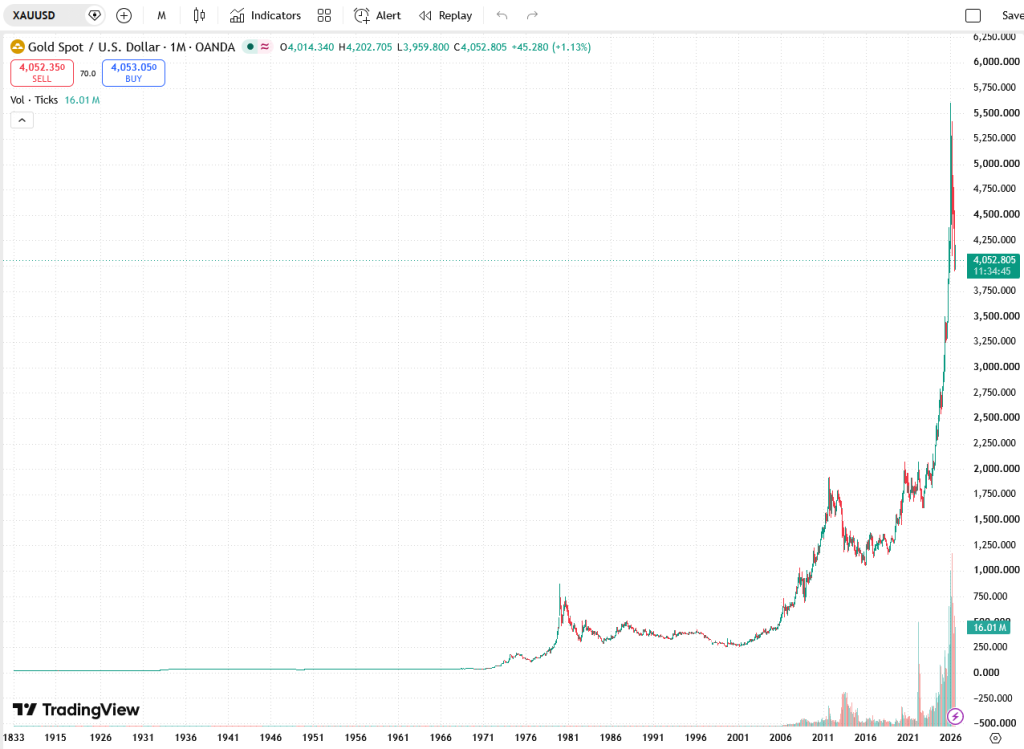
Now turn it upside-down…
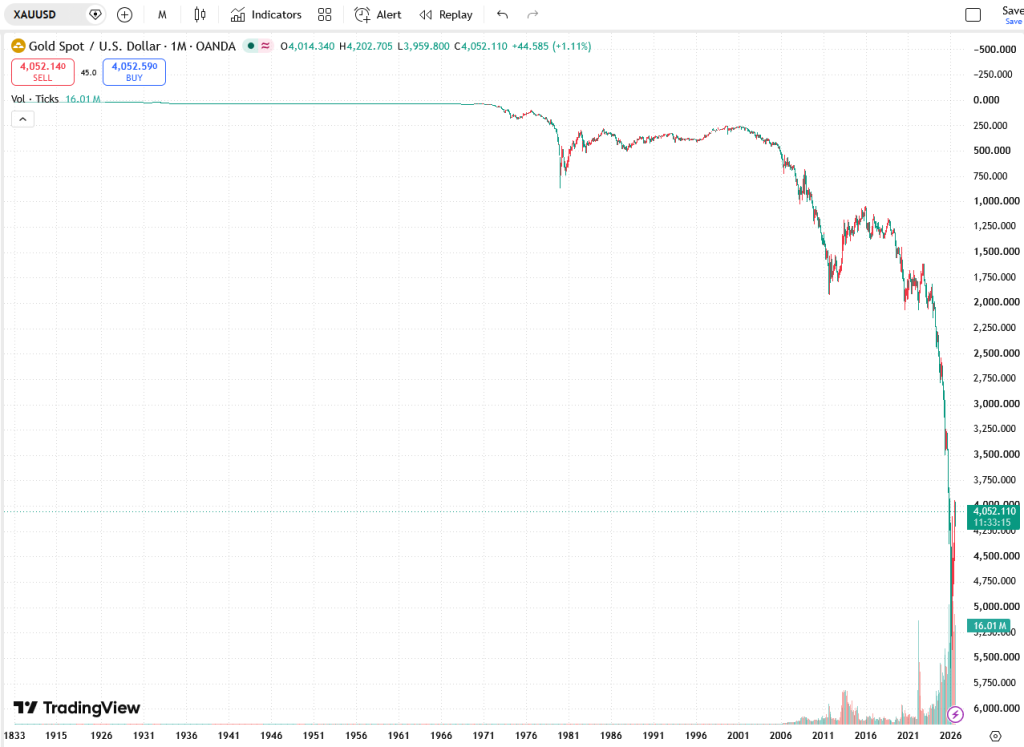
That’s your national currency dying!
Stop saving in dumb dollar debt and keep inflation at bay with gold.
Gold will protect your savings from being eaten away by inflation. As the cost of living rises, the price of gold similarly rises, protecting your purchasing power.
But that only helps your savings, not your earnings, so let’s look at that next…
Cost of Living Solution #2 – Master the art of getting a raise / pay-rise
A 5% raise used to seem good to me back when Headline CPI was 2% and I didn’t understand the hidden mechanisms behind the financial system.
Then I discovered that Headline CPI was just… a… headline… for news outlets to feed to the public, while the real inflation figures that the central banks actually pay attention to are kept behind the scenes; not secret, but not advertised like CPI. Indeed, CPI is about as accurate as the average goon trying to shoot James Bond.
So, don’t get complacent with any wage denominated in the national currency.
Look at your actual living costs (without trading down from rib-eye steak to minced beef or chicken) – how much has the lifestyle you actually want risen in cost in the last year?
If your raise hasn’t beaten that number, you’re going backwards!
A nominal raise on paper, but a pay-cut in terms of real purchasing power.
Learn how to show those numbers to your employer, how to make them understand that you can’t continue to give them your valuable time if the compensation you’re given is worth less and less each year, despite the higher number.
And be ready to apply for new roles if any resistance is offered to your requested pay.
Master the art of writing a brilliant résumé that gets past the AI-résumé-reader-bot’s age discrimination filter and puts your best foot forward to hiring managers. Write a cover letter that gives the hiring manager something to remember you by instead of putting them to sleep.
When you have more job offers from more companies, you also have more leverage to negotiate salary with your existing employer if that’s where you’d like to stay.
Now, working for someone else isn’t everyone’s cup of tea and it also makes scaling your income a harder task, so let’s look at tip #3.
Cost of Living Solution #3 – Build a side-hustle into a scalable business
An employee’s income can only grow so much. Even after mastering the résumé and the cover letter and the interviewing and pay-review processes, you might be able to grow your income by 20-25% per year with a lot of skill and good looks.
But unless you climb to the absolute top of the corporate ladder and become CEO of some mega-corporation, you won’t be turning a 5-6 figure salary into a 7-8 figure salary; 10xing or 100xing your income isn’t a realistic goal for an employee.
Enter the side-hustle. In all likelihood, it’s going to earn you next to nothing for the first year or two while you figure things out, I can tell you that from experience.
However, with the right business-model and a tonne of determination (or a dash of luck), you can build something that makes your cost of living something that you used to think about once upon a time.
Need more help addressing your cost of living?
- Were you surprised that bank deposits are a loan to the bank or that banknotes are debt instruments?
- Want to know more about how to buy physical precious metals, how to test them for purity & authenticity, where to store them, how to keep them safe?
- Would you like someone to go over your financial position with you, audit your spending and savings habits, help you pay down your debts, get a better deal on your mortgage, or other bills?
My goal is to help as many people make the most of their lives as I possibly can. If you’d like my help with anything, please check out the services I offer here at Primed For Life and reach out if you’d like to get my help.
I also have an eBooks available for those wishing to learn more on a tighter budget, including Muggle Money Magic, which goes into more details about the pros and cons of the various monetary products we use in day-to-day life.
That’s it for today’s article and I look forward to helping you get Primed For Life!
~Riley Fox
Leave a Reply